 hamster-bot
DoubleDragon
This is still the same ZigZag strategy. But we work a little differently. The whole difference is in how we look at the backtest, using the ratio chart of two coins XXXUSDT/xxxusdt.
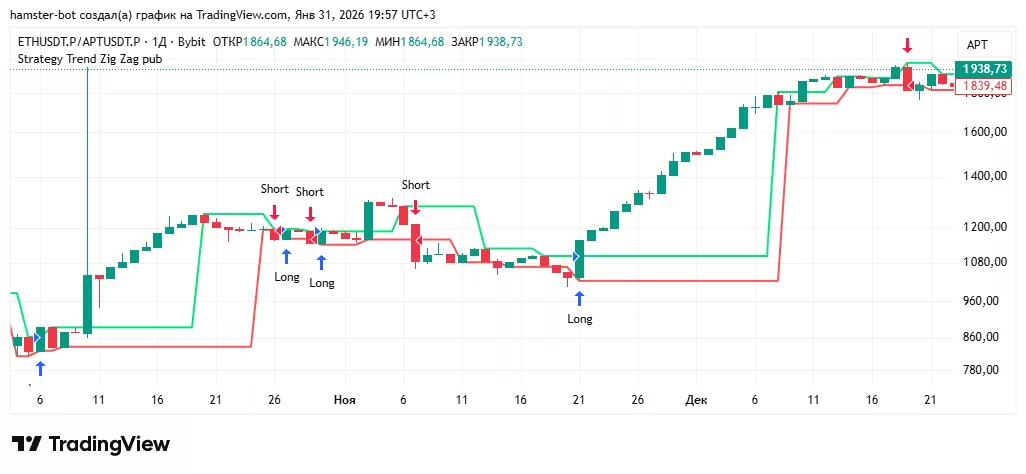
Wherever the synthetic chart in the strategy tester opens a Long position, on the real market a Long is opened on XXXUSDT and a Short on xxxusdt.
Wherever a Short position is opened, on the real market a Short is opened on XXXUSDT and a Long on xxxusdt.
Backtest
Test in the built-in backtester
A Pine Script for testing the strategy on historical data in the TradingView strategy tester:
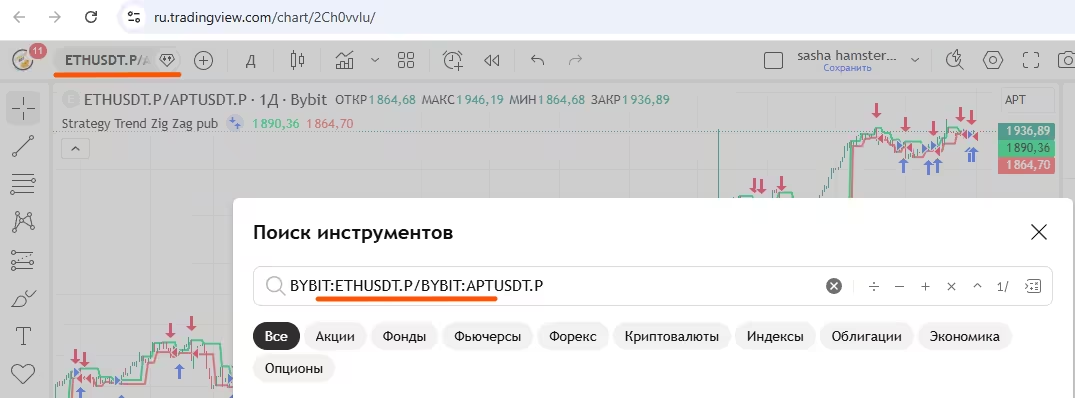
But as the input in the strategy tester we choose a synthetic chart instead of a single trading pair.
A synthetic chart of the ratio BYBIT:XXXUSDT.P/BYBIT:xxxusdt.P (where XXX is any cryptocurrency with a price higher than xxx)
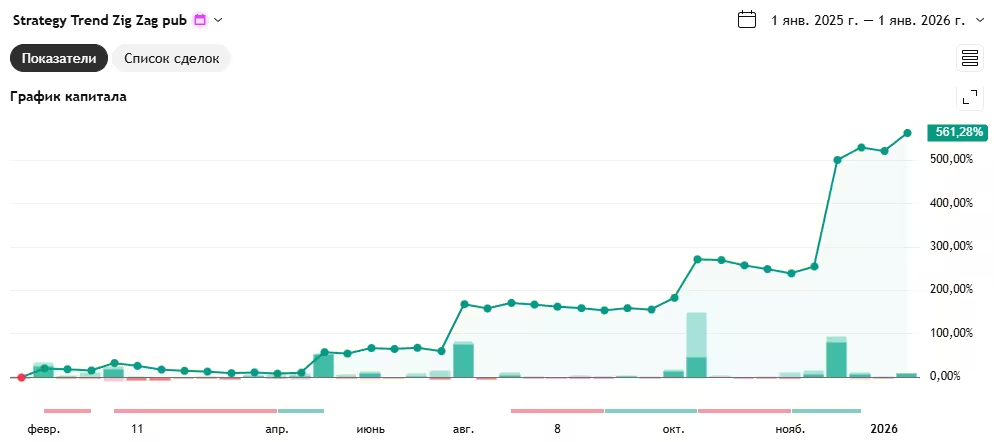
Strategy tester result for 2025 on BYBIT:ETHUSDT.P/BYBIT:APTUSDT.P on the 1d timeframe:
Backtest the strategy on historical data in the tester and run it in hamster-bot.